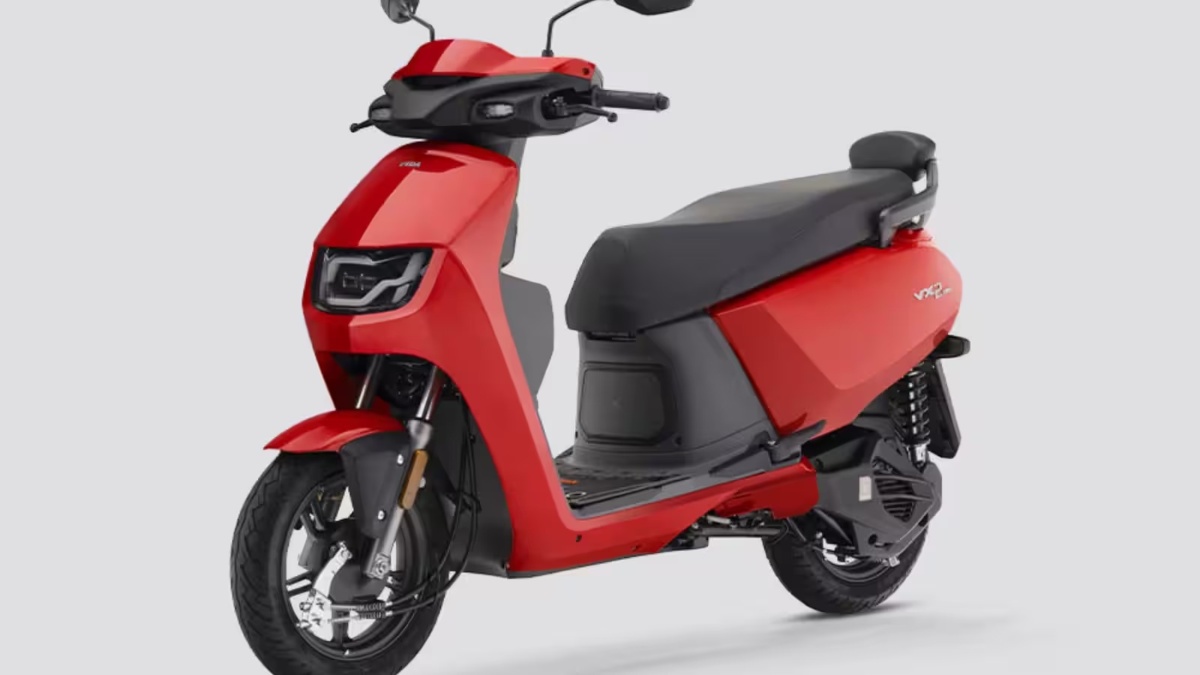
Business Desk – Ather Energy Share Rally: Shares of electric two-wheeler manufacturing company Ather Energy saw a rise of about 1% on Tuesday. The company's shares reached a high of Rs 1,621 during trading. This rise in the stock came when brokerage firm Bank of America Securities started coverage on the shares of Ather Energy and advised to buy it.
Bank of America gave a target of Rs 1,900
Bank of America Securities has started coverage on Ather Energy's shares and has given it a Buy rating. The brokerage has set a target of Rs 1,900 for the share. This target shows a potential upside of about 20% from the previous closing price.

The brokerage believes that the use of electric vehicles in India is now entering a period of rapid growth. Ather Energy has been considered one of the leading companies in this growing market.
16% share in electric two-wheeler market
According to Bank of America, Ather Energy has now moved beyond the early stage business proofing stage. The company has about 16% share in the electric two-wheeler market and is among the top three companies in the country.
Apart from this, the company is also getting premium prices for its electric scooters. That means customers are ready to pay relatively higher prices for Ather scooters.
Expanding business will be the next big challenge
According to the brokerage, now the further growth of Ather Energy will depend on how widely the company is able to expand its business. For this, Konark Platform, EL Platform and Auric are expected to increase the company's market reach and production capacity.
According to the brokerage, at present the demand for Ather's electric scooters is more than the available supply. In such a situation, increasing production will be important for the company in the coming times.
Profits can benefit from cost reduction
Bank of America believes that Ather Energy's profit margin may also increase further. With the help of EL platform, the company is expected to reduce the cost of manufacturing a vehicle i.e. bill of materials by about 8-10%.
Apart from this, as the company's business grows, it can also get the benefit of operating leverage. In simple language, as the level of production and sales increases, the company can control its costs better.
Margin expected to increase by FY 2031
According to the brokerage firm, Ather Energy's EBITDA margin could improve due to the twin benefits of cost reduction and increased business size. It is estimated that by FY 2031, the company's EBITDA margin may reach the low-teens of 10%.
Thus, according to the brokerage, the increasing demand for electric two-wheelers in India, Ather's current market share, ability to increase production and possible reduction in costs can become important bases for the company's further growth.