Investors demand predictability
Vietnam’s foreign direct investment (FDI) strategy is entering a new phase after nearly four decades of courting overseas capital. The earlier task was to make the environment attractive enough to draw international cash. The tougher challenge now is keeping quality capital, getting investors to expand and extracting more value for the economy.
With competition for FDI intensifying, multinationals weigh more than their tax bills. They also look at compliance costs, the risk of policy shifts, how rules are enforced and how long it takes to solve new problems. A clear, stable and predictable tax policy has become a core part of investment competitiveness.
Mai Xuan Thanh, Director of the Taxation Department, said companies also want to know whether policies are clear, obligations predictable and rules enforced consistently, and whether proper channels exist for dialogue and problem-solving when issues arise.
|
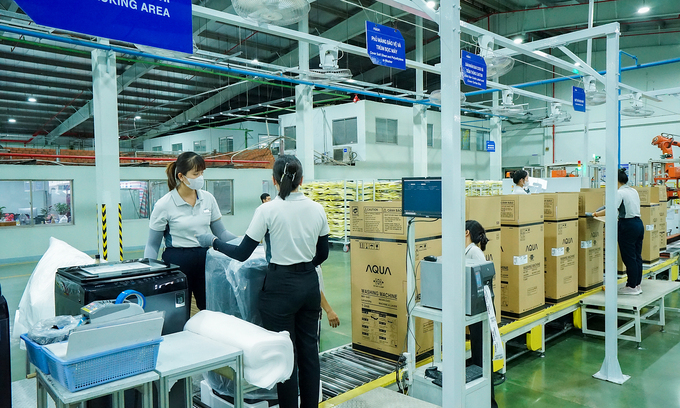
Workers inside a washing machine and refrigerator factory of AQUA Vietnam in Bien Hoa, Dong Nai City, January 2026. Photo by Read/Bao Lam |
The demand is sharpest for foreign-invested firms, whose production and trade often span multiple markets, entities and tax systems. Related-party transactions, double taxation avoidance agreements, advance pricing agreements, information exchange and data transparency can directly affect costs and planning.
From tax incentives to long-term investment climate
Nguyen Anh Tuan, Deputy Director of the Foreign Investment Agency under the Ministry of Finance (MoF), said the goal is no longer simply to raise capital volumes or project counts. Authorities want better quality, efficiency and sustainability in capital flows, and closer links between the FDI sector, domestic capabilities and long-term development goals.
That shift is set out in the Politburo’s Resolution 10-NQ/TW dated June 8, 2026 on developing the foreign-invested sector. It calls for moving from scale and quantity toward quality, efficiency and added value, and prioritises projects with advanced technologies, modern governance and innovation capacity that can plug deeper into global value chains.
Roux Eloïse, a representative of the European Union Delegation to Vietnam, said predictability is key for countries seeking to attract and keep foreign companies. Vietnam holds considerable advantages in its domestic market, infrastructure, logistics and network of free trade agreements, but a transparent, stable legal and tax environment will unlock more room for investment cooperation.
On Sept. 22, 2026, the government issued the Resolution 280/NQ-CP on an action plan to realize the Resolution 10-NQ/TW that assigns 61 tasks to ministries, agencies and localities. The MoF was assigned 22 key tasks covering direct and indirect investment and capital market development.
Tighter coordination among investment, tax and customs authorities is central, both to ease business operations and ensure policies are enforced as intended. Alongside improved investment legislation, tax administration should rest on data and risk management, so firms can comply proactively.
Thanh stressed that “transparency is a requirement for both sides”. Companies must ensure records and data truthfully reflect the substance of transactions and engage in dialogue early when complex issues arise. Tax authorities, in turn, need to publish policies, give clear guidance, enforce rules consistently and deliver information in a timely manner.