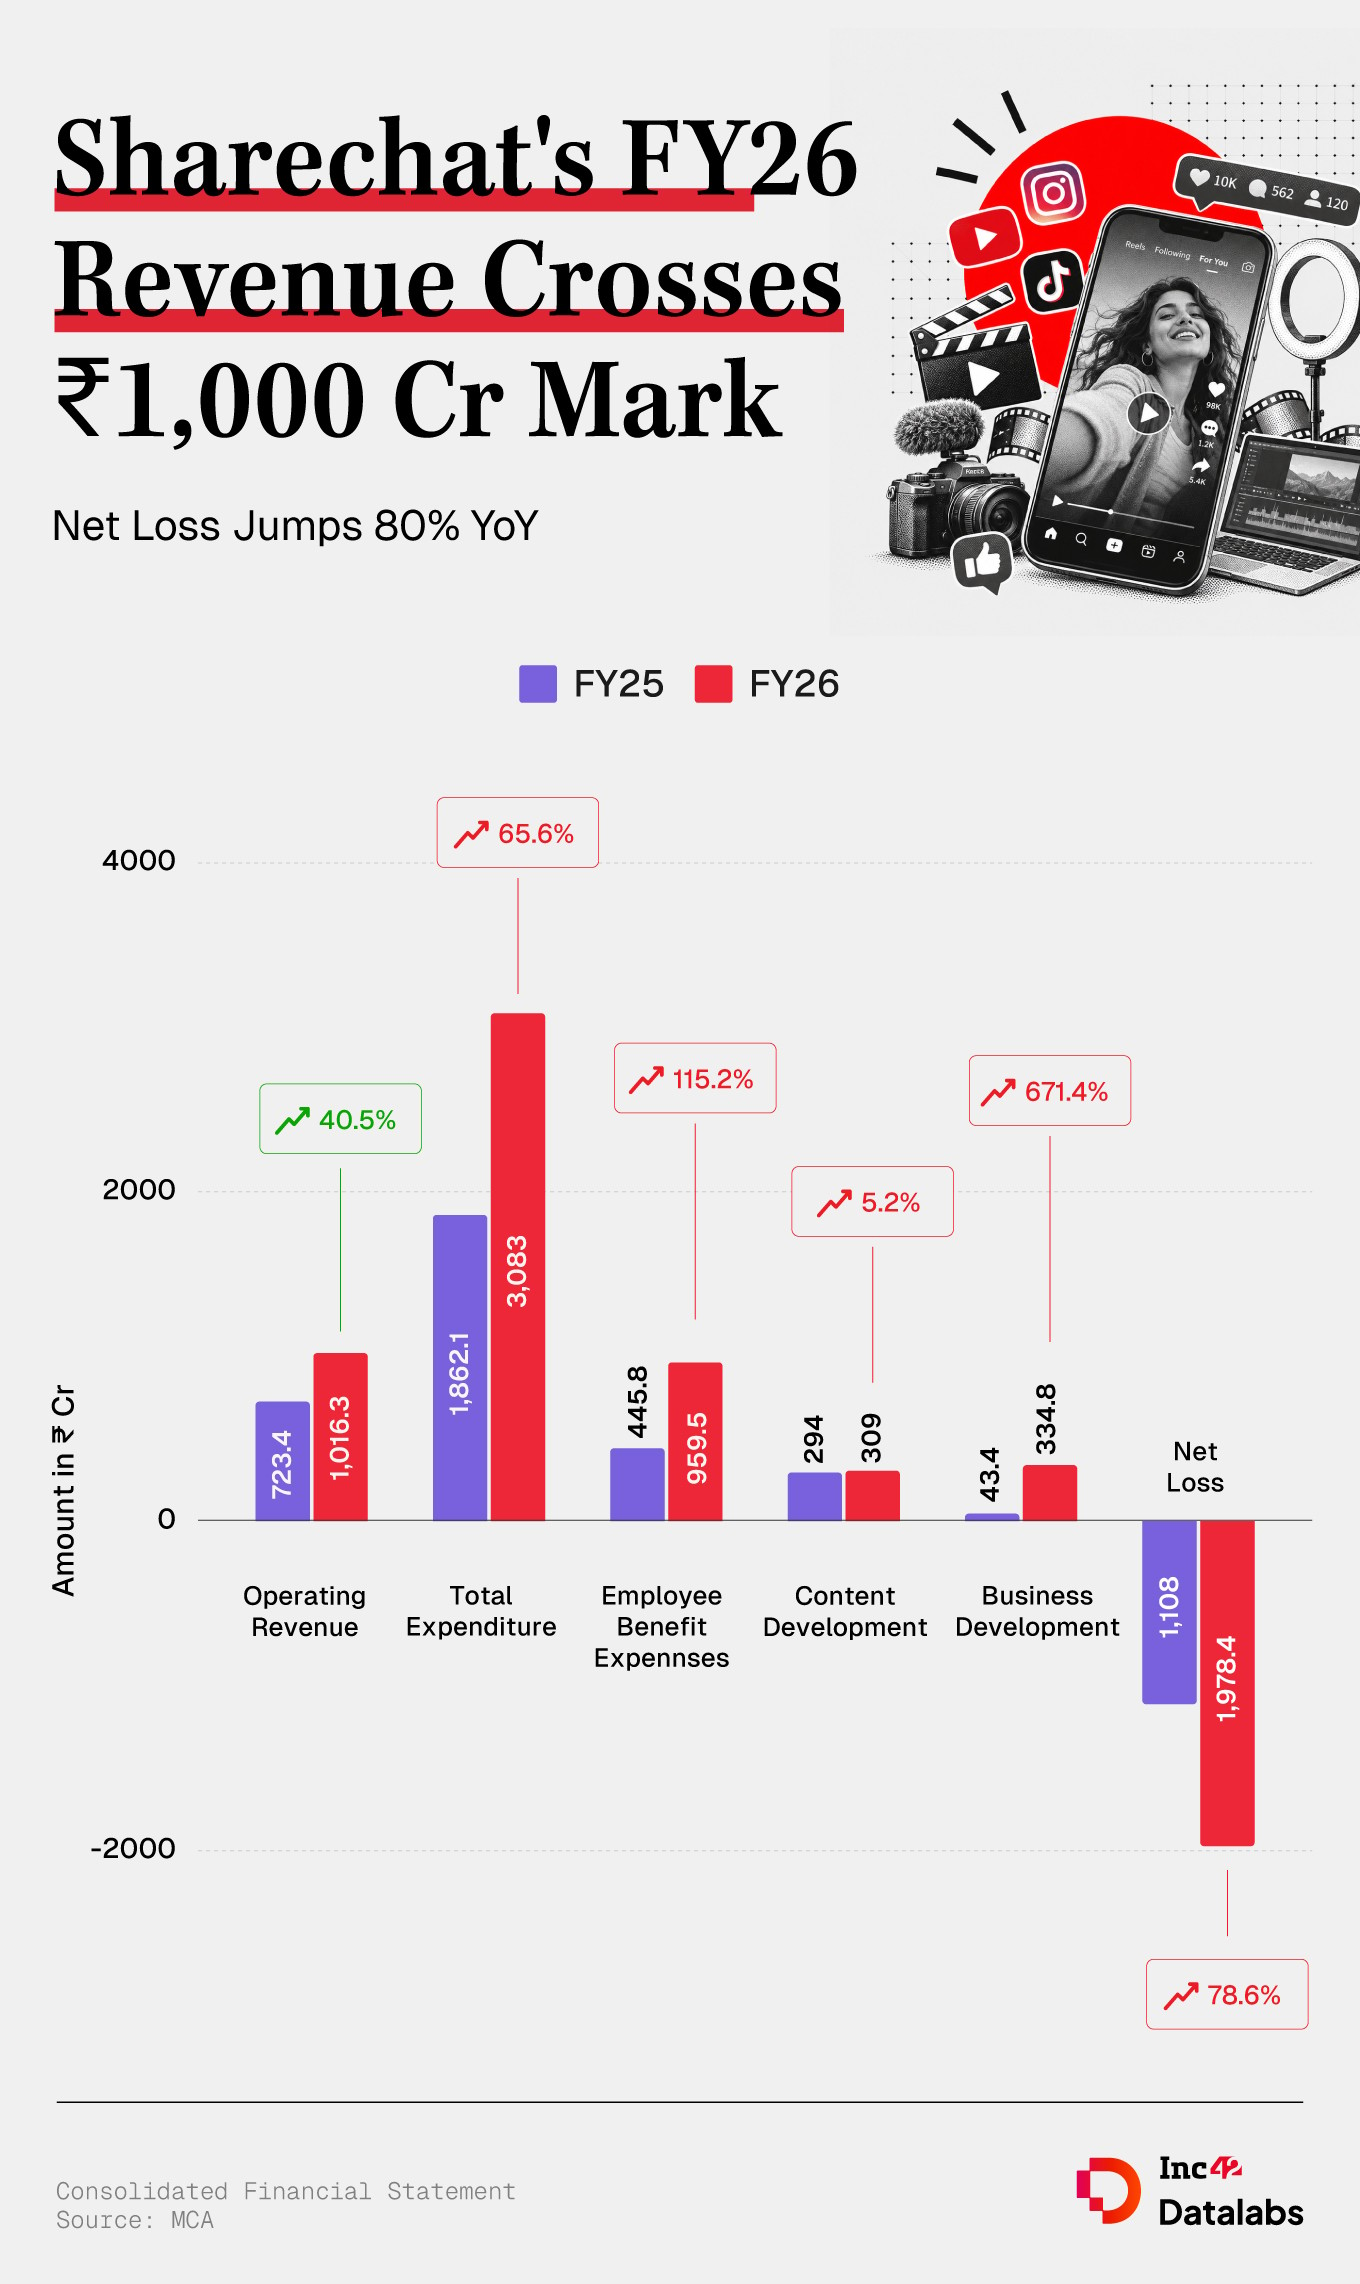
ShareChat parent Mohalla Tech’s consolidated net loss widened 78.5% YoY to ₹1,978.4 Cr in FY26, even as operating revenue jumped 40.4% to ₹1,016.3 Cr
Subscription revenue from its microdrama push helped offset declining advertising revenue, while the company narrowed its EBITDA loss by 58%
Higher ESOP expenses, forex losses and finance costs weighed on profitability, with total expenses jumping 65.6% YoY
Mohalla Tech, the parent of social media platforms ShareChat and Moj, reported a 78.5% YoY increase in its consolidated net loss to ₹1,978.4 Cr in the financial year ended March 2026 (FY26), weighed down by higher share-based payment expenses, foreign exchange losses and finance costs.
The loss for the fiscal year widened despite a 40.4% jump in operating revenue to ₹1,016.3 Cr from ₹723.4 Cr in FY25.
Further, the startup also reported an improvement in its operating performance. ShareChat’s management claims that it managed to narrow its FY26 EBITDA loss by 58% YoY to ₹91 Cr and recorded its first EBITDA positive quarter in Q1 FY27.
The company reported an EBITDA profit of ₹9.5 Cr and a margin of 0.3% in the June quarter. Its EBITDA margin improved to over 2% in Q2 FY27, the management claimed.
QuickTV Subscription Drives Revenue Growth
The startup’s management said its FY26 top line growth was led by the launch of QuickTV, its subscription-based microdrama platform launched in February 2025.
The subscription vertical, which accounts for subscriptions from both Quick TV and Moj (Moj+ and Moj Blue), raked in a revenue of ₹292.7 Cr in the fiscal, accounting for almost 30% of the top line in the fiscal.
Mohalla Tech had counted advertising and livestreaming as its two major pillars for revenue generation since its inception over a decade ago. In the previous fiscal year, it aggressively expanded into monetising the content on its platform amid a growing fervour for microdramas in the Indian content landscape.
Hailed as the “next phase of evolution for the entertainment industry“, Microdrama adoption picked pace in the Indian market early in FY26. ShareChat had launched its vertical microdrama platform, QuickTV, earlier in February 2025. Since then, the app has been downloaded by over 5 Cr users from the Google Play Store.
As its content monetisation took shape, the social media unicorn faced some operational turmoil for its long-set revenue driver — advertising.
Advertising revenue dipped 13% YoY to ₹251.8 Cr in the fiscal year. This decline came as advertisers from the real money gaming (RMG) stopped promotional spends. To note, ShareChat had already diversified its offerings for clients across FMCG and mid-market advertisers. Hence, it managed to offset the dent anticipated from the RMG ban.
On the other hand, ShareChat’s livestreaming segment grew almost by 9% YoY to ₹471.8 Cr. This segment registers revenue from paying users on both ShareChat and Moj platforms.
ShareChat’s FY27 Outlook
For the fiscal year FY27, Mohalla Tech is targeting an EBITDA profit of ₹25 Cr, including at least ₹15 Cr in the second half of FY27.
The startup reported around ₹740 Cr in revenue in the first half of FY27, while its Q2 FY27 annualised revenue run rate reached approximately ₹1,500 Cr. It did not disclose its bottom line performance for the September half of the ongoing fiscal.
To fuel this financial improvement, the startup is expecting both of its content monetisation models — subscription video on demand (SVOD) and advertising-based video on demand (AVOD) — to shoulder its next phase of growth.
ShareChat is expecting its advertising to make a stronger contribution in FY27, growing by 40% YoY. While it is expecting its AVOD revenue to surpass the ₹350 Cr mark, this particular revenue stream touched ₹160 Cr in the first half.
The management didn’t share any projections for revenue from SVOD in the fiscal. It believes that most Indian internet users are unlikely to pay for microdrama subscriptions, with the number of paying users for the format expected to remain below 100 Mn even as the market matures, making advertising an important monetisation opportunity.
The Microdrama Dillema
Mohalla Tech’s push into microdrama comes as the format draws growing interest across businesses.
EloElo Group, the parent of microdrama platform Story TV, recently raised $80 Mn (around ₹756 Cr) in a Series C round led by Hornbill Capital and NBCUniversal. The company plans to invest in original content across Indian languages, expand Story TV internationally and strengthen its AI-powered production capabilities. Story TV has more than 5,000 microdramas across six languages, while EloElo claims over 40 Mn monthly active users across its apps.
The space has also attracted startups such as Kuku TV, Flick TV, ReelSaga and Chai Shots, alongside larger platforms including JioHotstar’s Tadka, Zee Entertainment’s Bullet and Amazon MX Player’s MX Fatafat. Businesses and platforms are utilising the short-story format to plug in marketing and products while capitalising on the rise in vertical content consumption.
What’s New: ShareChat parent Mohalla Tech’s consolidated net loss widened 78.5% YoY to ₹1,978.4 Cr in FY26, even as operating revenue jumped 40.4% to ₹1,016.3 Cr.
Why It Matters: Subscription revenue from its microdrama push helped offset declining advertising revenue, while the company narrowed its EBITDA loss by 58%.
The Details: Higher ESOP expenses, forex losses and finance costs weighed on profitability, with total expenses jumping 65.6% YoY.
However, rising customer acquisition costs and the difficulty of converting free viewers into paying subscribers continue to weigh on the economics of standalone microdrama platforms. For instance, Mohalla Tech said acquiring a user on its free-to-use platform Moj costs around ₹14-15 per download, while acquiring a paying subscriber for QuickTV costs hundreds of rupees, given the latter’s newer brand and subscription paywall. It claimed that competing subscription platforms could be spending upwards of ₹1,000 per subscriber.
Owing to this, platforms like Mohalla Tech are instead banking on advertising revenue and marketing plug-ins to increase monetisation.
Where Did ShareChat Spend In FY26?
Mohalla Tech’s total expenses surged 65.6% to ₹3,083 Cr in FY26 from ₹1,862.1 Cr a year earlier.
During its FY26 earnings call, management said the reported loss was largely driven by non-cash and notional accounting items, including provisions for interest on hybrid debt instruments, unrealised foreign exchange losses and ESOP expenses.
Employee Benefit Expenses: Expenses under this head more than doubled to ₹959.5 Cr from ₹445.8 Cr in FY25. A large part of the increase came from share-based payments, which climbed 302% to ₹739 Cr in FY26 from ₹183.8 Cr in FY25, following an expansion of the company’s ESOP pool and additional grants to key employees.
Foreign Exchange Losses: Owing to rupee-dollar depreciation, non-cash expenses under this head rose more than fourfold to ₹566.9 Cr from ₹128 Cr in FY25. The increase was largely driven by unrealised forex losses of ₹566 Cr.
Business Development: Expenses under this head, which usually covers functions like marketing, promotions and customer acquisition, surged 7.7X to ₹334.8 Cr from ₹43.4 Cr in FY26.