Olyv has raised $6 Mn from Nippon Life India AIF Management Ltd and existing investors in an extension of its Series B round
It is looking to expand beyond digital lending into a broader financial services ecosystem targeting underserved consumers across India, starting with health insurance and credit health management
The startup plans to invest in AI, underwriting technology, and product portfolio expansion as it targets 100 Mn users and over $1 Bn in AUM by FY29
Despite advances in financial inclusion, a large section of India’s salaried and self-employed population continues to struggle to access formal credit. The challenge is particularly pronounced in smaller towns, where borrowers often lack conventional income documentation or established credit histories.
Fintech startup Olyv is looking to bridge this gap by expanding beyond digital personal loans into a broader financial services ecosystem focused on credit access and financial health.
Founded in 2016 by Rohit Garg, Amit Chandel, Vinay Singh and Jayant Upadhyay, the startup has raised $6 Mn (around ₹57 Cr) from Nippon Life India AIF Management Ltd and existing investors. The latest fundraise takes its total equity capital raised to around $50 Mn. Olyv has also raised $150 Mn in debt funding since inception.
The latest investment is an extension of its $23 Mn Series B round in February, led by Nandan Nilekani-backed Fundamentum Partnership.
In a conversation with Inc42, CEO and cofounder Garg said the fresh capital will primarily go towards investments in AI and data science to strengthen the company’s proprietary underwriting technology. These investments are aimed at improving risk assessment and personalising financial products, particularly for customers outside India’s major metropolitan markets.
Olyv also wants to deepen its engagement with existing customers by introducing products beyond personal loans. In the near term, it plans to expand into health insurance and credit health management.
The startup is also developing AI-powered financial advisory services to help customers understand their financial data, improve their credit scores and make better financial decisions.
“The idea is that there should be a personalised companion which can help people build their credit scores and manage their data. AI advisory will help them look at their data deeply, advise them and guide them towards actions to create a much stronger credit profile,” Garg said.
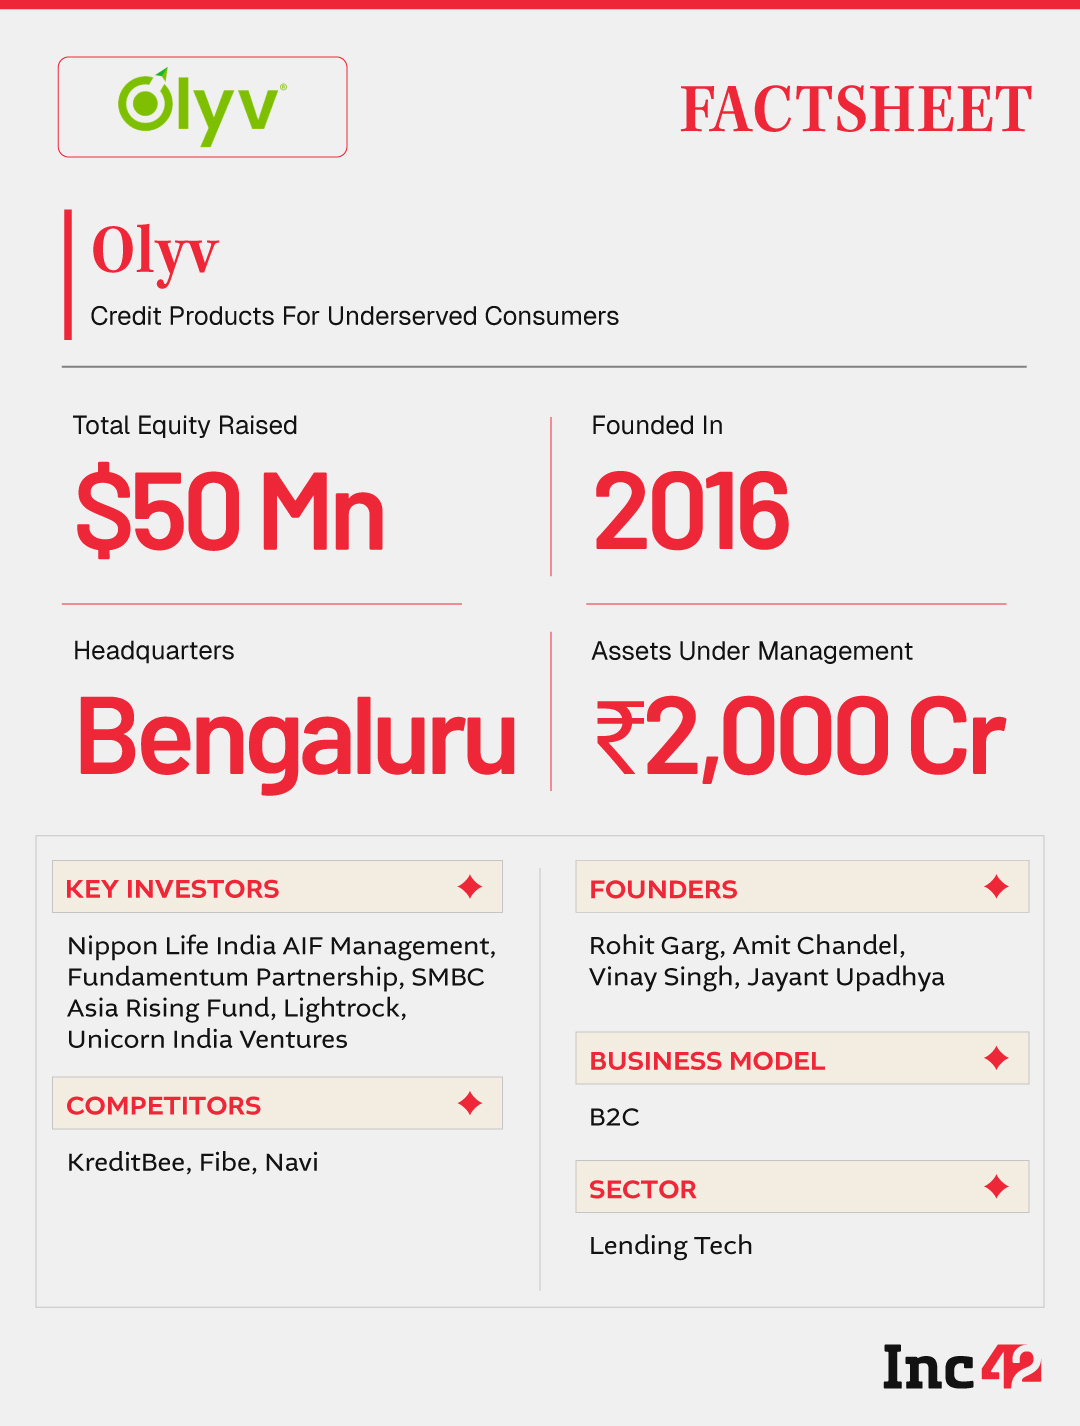
Olyv operates in a competitive digital lending market, where fintechs such as Navi, KreditBee and Fibe are vying for a larger share of India’s consumer credit market.
However, Garg believes the market is expanding fast enough to accommodate multiple players, with digitisation and financial inclusion bringing more consumers into the formal financial system.
“While the top 50-100 Mn consumers in India are adequately served by large institutions, the next 200-300 Mn is where I believe the next phase of growth over the next decade will come from, and I think Olyv will play a significant role in that,” he said.
The startup claims that 70-75% of its customers come from Tier II, III and IV towns. These include micro-merchants running small neighbourhood businesses, freelancers and salaried employees working with smaller organisations.
Olyv currently has nearly 2 Mn monthly active users and more than 50 Mn app downloads, with a presence across over 19,000 pin codes. It has disbursed approximately 80 Lakh loans, facilitating cumulative transactions worth more than ₹13,000 Cr.
According to Garg, the company currently manages assets under management (AUM) of nearly ₹2,000 Cr. It is targeting 100 Mn users and AUM of more than $1 Bn (around ₹9,348 Cr) by FY29.
While Garg declined to disclose the company’s absolute financials, he said revenue grew around 50% year-on-year (YoY) in FY26, while profit after tax (PAT) increased 80-90%. Olyv also claims to have recorded sequential PAT growth for 14 consecutive quarters.
Olyv has built a sizable digital lending business by targeting consumers who often remain underserved by traditional financial institutions. Its reported profitability and loan disbursement numbers suggest that it has established a meaningful presence in this segment.
However, expanding from lending into a diversified financial services business is a considerably bigger challenge. Offering health insurance, credit management and AI-led financial advisory services will require capabilities beyond underwriting and loan distribution.
The immediate test will be whether Olyv can convert its existing customer base into users of these additional services. A large lending customer base offers a distribution advantage, but it does not automatically translate into demand for insurance or financial advisory products.
The startup will also need to demonstrate that these new verticals can generate meaningful revenue without disproportionately increasing customer acquisition and operating costs.
There is also the question of asset quality. As Olyv expands its lending business among customers with limited formal credit histories, maintaining underwriting discipline will be critical. Investments in AI and data science could strengthen its risk assessment capabilities, but the effectiveness of these systems will ultimately be reflected in loan performance.
Olyv’s ambition to reach 100 Mn users and cross $1 Bn in AUM by FY29 is therefore not just a question of scaling its existing lending business. It will need to show that it can build commercially viable financial services around that lending base while maintaining profitability and asset quality.