
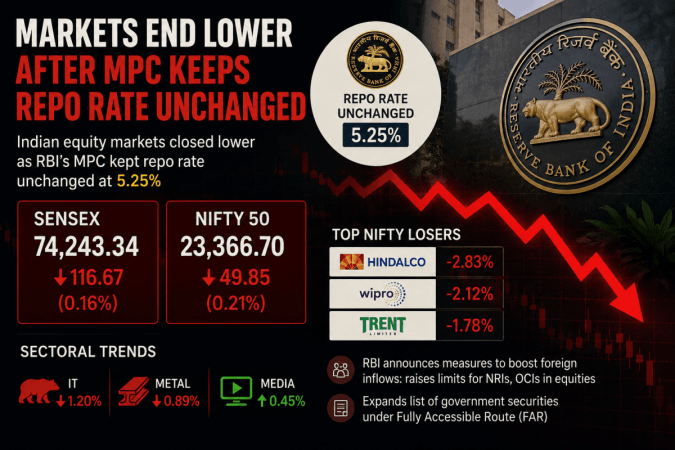
Mumbai witnessed a decline in domestic equity benchmarks on Wednesday morning as cautious investors awaited the Reserve Bank of India’s upcoming monetary policy decision amid mixed global cues.
The Sensex fell sharply by up to 462.44 points, or 0.63 per cent, settling near 72,605.37, while the Nifty index dropped 175.65 points, or 0.77 per cent, to 22,600.
At market open, the BSE Sensex and Nifty 50 stood at 72,965.38 and 22,690.45, respectively.
Among sectoral indices, Nifty Consumer Durables led losses with a 1.55 per cent decline, followed by Nifty Metal, which slipped 1.34 per cent, and Nifty Auto, down over 1 per cent. Other notable decliners included Nifty PSU Bank down 0.94 per cent, Nifty Oil & Gas 0.82 per cent lower, and Nifty Realty and FMCG falling up to 0.7 per cent.
Healthcare and pharmaceuticals provided some respite, with Nifty Pharma rising 0.16 per cent and Nifty500 Healthcare gaining modestly; Nifty Media advanced 0.74 per cent.
Market watchers are tracking crude oil prices, foreign portfolio investor flows, the rupee’s performance, and the RBI’s assessment of growth and inflation trends.
noted, “The 558 point rally in the Nifty from last Thursday’s low has been a relief but faces headwinds. Brent crude oil has reclaimed levels above $101, and foreign portfolio outflows continue, though domestic liquidity and expectations of strong Q2 earnings are sustaining the market.”
They added, “The market will focus on the RBI Governor’s stance today. A 25 basis point rate hike is almost certain and priced in. What matters is the monetary policy’s stance and RBI’s outlook on growth and inflation.”
indicated the market response will hinge on the Governor’s comments on the economic outlook, noting the narrow interest rate differential between India and the US.
They remarked, “A rate hike to curb further capital outflows seems necessary given rising US yields and dollar strength. Stabilising the rupee will also be a priority, though the focus remains on the growth-inflation balance.”
Technical analysts stayed positive despite anticipating short-term volatility.
One expert said, “Yesterday’s relief rally paused near 22,800 as expected, but we look forward to further gains targeting 22,930 to 23,220, although dips are likely today.”
They cautioned, “Failure to rise above 22,690 could trigger volatility, but upswings should resume if dips stay above 22,574. No collapse below 22,050 is expected soon.”
Meanwhile, Asian markets showed mixed performance on Wednesday, influenced by Wall Street’s latest gains, high US Treasury yields, and ongoing geopolitical strains. US equities rose on Tuesday as stabilising oil prices and retreating Treasury yields eased some pressure ahead of the third-quarter earnings season.
Crude oil prices rose on Wednesday due to concerns over supply disruption from an approaching US storm and attacks on Saudi Arabia by Houthis, despite increased crude shipments from the Middle East.