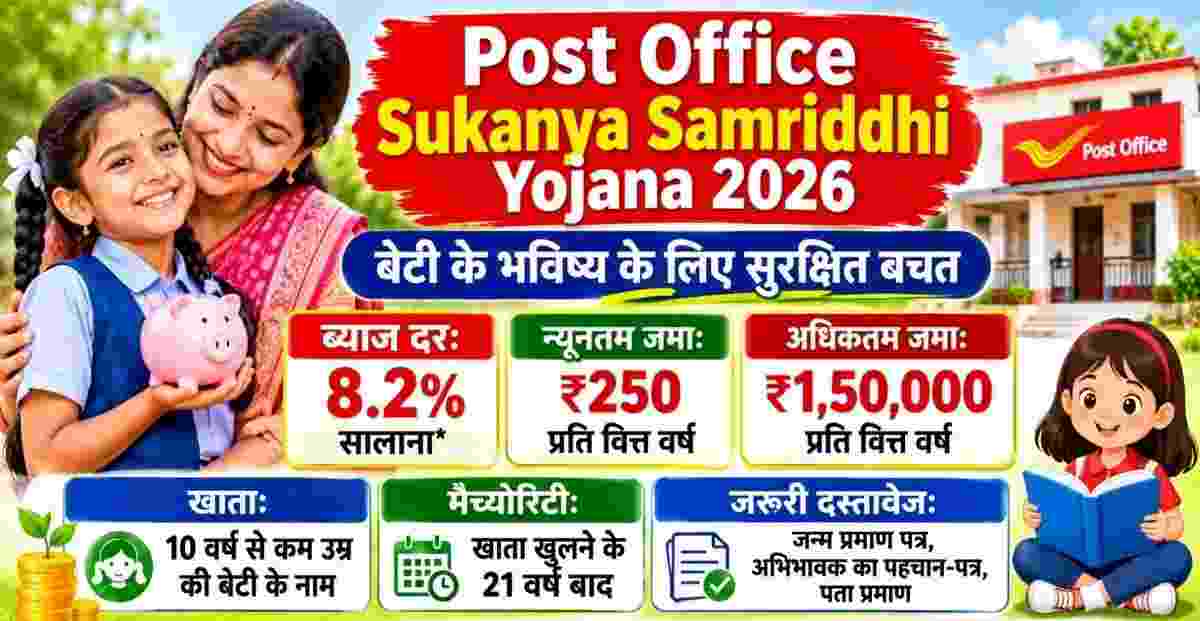
In the times of stock market fluctuations and fluctuating returns, small savings schemes of India Post are considered to be the most reliable option among common citizens for traditional and safe investment. Being protected by the Sovereign Guarantee of the Central Government, the depositors' capital remains completely risk-free and fixed returns are guaranteed. Many popular schemes are being operated in the post office for secure future, regular monthly income, retirement fund and higher education of daughters under interest rates fixed on quarterly basis by the Finance Ministry. If you are also planning to invest in savings schemes, then it is important to understand the complete information about interest rates, investment limits and tax exemptions of Recurring Deposit (RD), Time Deposit (FD), Public Provident Fund (PPF), Monthly Income Scheme (MIS), Senior Citizen Savings Scheme (SCSS) and Sukanya Samriddhi Yojana (SSY). Major Post Office Savings Schemes and Current Interest Rates (Comparative Chart) Scheme Name Scheme Name Annual Interest Rate Investment Tenure Minimum/Maximum Investment Limit Tax Benefit Post Office RD (5-Year RD) 6.70% 5 years Minimum ₹100 per month (no maximum limit) Interest Taxable Time Deposit / FD (1, 2, 3, 5 years) 6.90% 7.50% 1 to 5 years Minimum ₹1,000 (no cap) Section 80C rebate on 5-year FD Public Provident Fund (PPF) 7.10% 15 years Minimum ₹500, maximum ₹1.5 lakh annually EEE Category (completely tax-free) Monthly Income Scheme (POMIS) 7.40% 5 years ₹1,000 to ₹9 lakh (single), ₹15 lakh (compound) Monthly Interest Taxable Senior Citizen Savings Scheme (SCSS) 8.20% 5 years (3 years extension) Min ₹1,000, Max ₹30 lakh 80C exemption, Quarterly interest Sukanya Samriddhi Yojana (SSY) 8.20% 21 years (15 years deposit) Min ₹250, Max ₹1.5 lakh annually EEE Category (Completely Tax-Free) 1. Post Office Recurring Deposit (Post Office 5-Year RD) 5-Year RD scheme is considered most suitable for middle class and employed people to develop the habit of regular monthly savings. Interest Rate and Calculation: Interest is given on this account at the rate of 6.70% per annum, which is calculated on quarterly compounding basis. Deposit Amount: This account can be opened with a minimum installment of just ₹100 per month and there is no limit on the maximum deposit. Account Tenure and Loan Facility: This account is opened for 5 years (60 months). After the account remains active for one year continuously, the facility to take loan up to 50% of the deposited amount is also available. Premature closure is allowed after completion of 3 years. 2. Post Office Time Deposit / Fixed Deposit (Time Deposit – POTD) Like the Fixed Deposit (FD) of banks, a lump sum amount is deposited for a fixed time in Post Office Time Deposit. There are tenors available in 1 year, 2 years, 3 years and 5 years: Interest Rates: 1-Year Time Deposit: 6.90% 2-Year Time Deposit: 7.00% 3-Year Time Deposit: 7.10% 5-Year Time Deposit: 7.50% Tax Benefits: Income tax only on the amount deposited in 5-Year Time Deposit account. Under Section 80C of the law, the benefit of tax deduction up to ₹ 1.5 lakh per year is available. Interest is calculated on a quarterly basis and paid annually. 3. Public Provident Fund (PPF) PPF is one of the most popular instruments in terms of long-term financial security, retirement corpus and tax savings. Interest and Tax Benefits: Currently, PPF is offering 7.10% annual interest, which is calculated compounded annually. The biggest attraction is that PPF has 'EEE' (Exempt-Exempt-Exempt) category status. This means that the amount invested (under Section 80C), interest earned and the entire fund received on maturity is completely tax-free. Rules: Minimum of ₹500 and maximum of ₹1.5 lakh can be deposited in a financial year. This account matures in 15 years, which can be extended in blocks of 5 years if required. 4. Post Office Monthly Income Scheme (Post Office MIS) For investors who want to receive a fixed income (monthly pension like income) every month by depositing lump sum capital, National Savings Monthly Income Account (POMIS) is the safest option. Interest and Monthly Returns: Currently the MIS scheme is offering an interest of 7.40% per annum. It is paid directly into the investor's savings account every month. Investment Limit: A maximum of ₹ 9 lakh can be deposited in a single account and a maximum of ₹ 15 lakh can be deposited in a joint account. Example: If you deposit ₹15 lakh in a joint account, at an interest rate of 7.4%, you will get a guaranteed monthly income of around ₹9,250 every month. The maturity period of this scheme is 5 years. 5. Senior Citizen Savings Scheme (SCSS) This scheme for senior citizens aged 60 years and above is on top of the highest interest paying safe options in the market. Interest Rate: SCSS offers an attractive interest rate of 8.20% per annum. Interest payment is credited to the investor's account every quarter (every three months). Investment Limit and Tax Exemption: A senior citizen can invest a maximum of ₹30 lakh in this account. The amount deposited is eligible for exemption up to ₹1.5 lakh under Section 80C of Income Tax. Tenure: The account matures in 5 years and can be extended for 3 additional years on completion of the tenure. 6. Sukanya Samriddhi Account (SSY) This is a special government savings scheme to secure the bright future and marriage expenses of the girl child under the 'Beti Bachao, Beti Padhao' campaign. Highest interest rate: Among small savings schemes, the highest interest rate of 8.20% per annum is being given on Sukanya Samriddhi Yojana. Interest is calculated on annual compound basis. Eligibility and Terms: This account can be opened in the name of girl children below 10 years of age by their parents or legal guardian. This account can be opened only for a maximum of two daughters in a family (three in case of twin girls). Deposit Limit and Maturity: Minimum of ₹250 and maximum of ₹1.5 lakh can be deposited in a financial year. The amount has to be deposited for 15 years from the date of account opening and the account matures when the girl turns 21 years of age or at the time of marriage after 18 years of age. Partial withdrawal up to 50% is allowed for higher education once the girl child turns 18. Like PPF, this scheme is also completely tax-exempt (EEE). Documents required for opening an account (KYC Checklist) To open an account in any post office savings scheme, the following identity and address documents have to be submitted to the nearest post office branch: Proof of Identity: PAN Card (PAN Card is mandatory) or Passport, Voter ID or Driving License. Proof of Address: Aadhar Card, Electricity Bill, Ration Card or Residence Certificate. Recent passport size photograph: 2 to 3 color photographs. Additional for Sukanya Samriddhi Yojana: Original Birth Certificate of the girl child. Additional for Senior Citizens Scheme (SCSS): Age certificate and document of superannuation (VRS/Superannuation). Post office savings accounts are also linked to India Post Payments Bank (IPPB) and mobile banking, allowing online fund transfer and installment payments from the comfort of home.