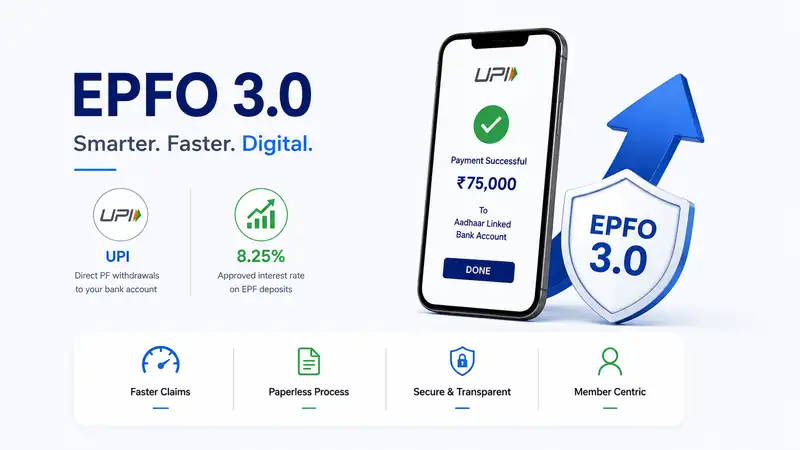
The Employees’ Provident Fund Organization (EPFO) is going to take a historic step towards making the withdrawal process completely digital and faster for its more than 7.5 crore active subscribers. The compulsion of filling the forms for a long time, waiting for the approval of the employer and waiting for 7 to 10 days for the money to come into the account is going to end soon. Under the government’s ‘EPFO 3.0’ digital reforms, subscribers will be able to withdraw their PF directly through Unified Payments Interface (UPI) and UPI-enabled ATMs. According to official sources and media reports, this system is being tested in collaboration with various banks and it is likely to be formally introduced by the end of December. However, until this service is fully rolled out, the existing UAN portal based claim process will continue.
The introduction of UPI based withdrawal does not mean that the subscriber will ever be able to withdraw the entire PF fund. Keeping retirement security in mind, EPFO has set strict financial limits for:
- Withdrawal up to maximum 75%: Under the new rules, eligible subscribers will be able to withdraw only a maximum of 75 percent of the total PF balance for their emergency or short-term needs through UPI.
- 25% Mandatory Floor: At least 25% of the total PF corpus will always remain locked in the account. This remaining amount cannot be withdrawn under any circumstances under partial withdrawal so that social security remains intact after retirement and the interest on it continues.
- Auto-settlement limit ₹5 lakh: Under EPFO 3.0, the limit for automatic claim settlement has been increased from ₹1 lakh to ₹5 lakh. This means claims up to ₹5 lakh from fully KYC verified accounts will be automatically approved by the system within a few hours without any human intervention.
- Daily and Transaction Limit: For security reasons, a maximum limit (up to approximately ₹1 lakh) per day/per transaction may be set for instant UPI and ATM withdrawals.
Earlier, there used to be dozens of different forms and rules for withdrawing advance from PF. Under EPFO 3.0, all these complexities have been reduced to three clear categories:
- Essential Requirements (Essential – Category 1): Partial withdrawal for medical emergency, marriage and higher education. There will be no minimum service period requirement for medical, whereas for marriage and education, up to 50% of the funds can be withdrawn as per the prescribed service conditions.
- Housing Requirements (Housing – Category 2): Withdrawal will be allowed up to 90% of the total balance for purchase or construction of a house and up to the prescribed limit for renovation of the house.
- Special circumstances (Special – Category 3): Immediate withdrawal of up to 75% after 1 month of job loss and 100% full settlement after 2 months or on retirement at the age of 58 years. Additionally, the biggest relief is that the requirement of digital signature or approval by the employer has been removed for most partial claims and self-certification is being recognised.
To avail this facility, it is mandatory for the shareholders’ records to be completely updated. The system may reject your claim if there are any deficiencies in your records:
- Activate UAN (Universal Account Number): Your UAN should be active and active on the portal.
- Aadhaar Linking (Aadhaar Seeding): It is mandatory to link Aadhaar card with UAN. Also, the mobile number linked to Aadhaar should be active so that OTP authentication can be done.
- PAN Card Verification: PAN verification is necessary to avoid tax deduction (TDS), especially for members whose service period is less than 5 years.
- Bank Account and IFSC Code: Your active bank account number and correct IFSC code should be entered in the EPFO database, so that the UPI ID can be matched easily.
The facility of withdrawing PF through UPI and ATM will prove to be no less than a financial lifesaver in emergency situations. You will no longer have to fall into the trap of taking out a loan or a high interest personal loan to meet sudden hospital bills or other urgent expenses. But financial experts clearly believe that the compound interest received on PF is the biggest capital for a secure future. The withdrawal process being easy does not mean that the PF account should be emptied to fulfill unnecessary expenses or hobbies. Use this digital facility only in genuine emergencies so that your retirement fund remains safe and sound.