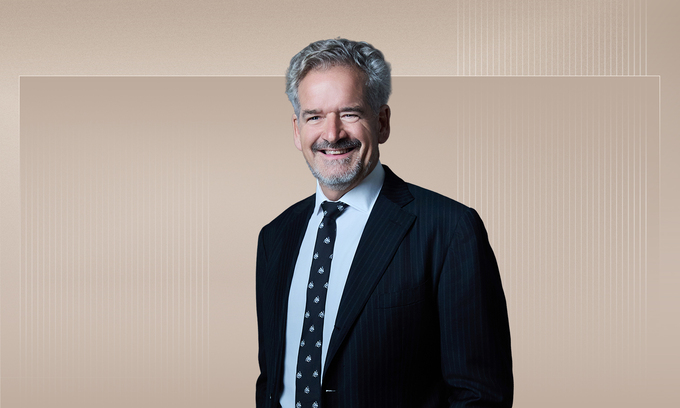
Eximbank independent director Michael Harte says stronger governance, empowered employees and responsible technology adoption can help the bank build customer trust and better serve
Vietnam’s growing businesses.
Harte has spent more than 35 years in financial services, technology and digital transformation. Yet during his first visits to Eximbank, it was the people, rather than the technology,
that made the strongest impression on him.
At the bank’s branches, he met dedicated frontline employees and saw similar commitment among risk and finance teams. He also encountered long-standing customers who remained loyal to
Eximbank and wanted to see it succeed.
The experience reinforced a belief shaped by his career helping major financial institutions navigate change: people are central to building a successful bank.
Harte’s connection with Eximbank began through a former colleague with whom he had worked at McKinsey and Commonwealth Bank of Australia (CBA) during a major transformation focused on
customer service and accountable governance. A subsequent meeting in Singapore to discuss Eximbank’s future convinced him to join the bank’s transformation journey.
He saw an established Vietnamese lender with deep roots in trade and corporate banking, as well as opportunities to strengthen customer relationships and better address their financial
needs.
Harte is now an independent member of Eximbank’s Board of Directors for the 2025–2030 term. His career includes senior roles at Citigroup, PNC Financial Services, CBA, Barclays and
Banco Santander. He is also a co-founder of CaptureNow and an Industry Research Fellow at the Massachusetts Institute of Technology (MIT).
Drawing on this experience, he believes the bank’s long-term development should be measured not only by its technological capabilities or scale, but also by how effectively it helps
customers achieve their financial goals.


For Harte, serving small and medium-sized enterprises (SMEs) means looking beyond individual loan applications to understand the businesses behind them.
He illustrates this with the example of a restaurant owner operating five outlets who plans to open two more and expand the workforce to 25 employees.
A conventional banking relationship might begin with questions about financing needs, collateral and loan approval. But expanding a business involves more than securing capital. The
owner must also manage cash flow, payroll, working capital and future expenses while deciding how to allocate available funds.
Rather than addressing these needs separately, a bank could build a broader relationship by offering cash management, payroll, treasury services, savings and suitable financing
solutions. It could also provide personal banking services to the owner and financial products to employees.
Harte uses the example to explain why banks need to understand the businesses they serve. For SMEs, which often have limited resources and increasingly complex financial needs,
relevant advice and services can be as important as access to financing.
He compares the role of a trusted financial partner to that of a “financial doctor.” Just as a doctor needs to understand a patient’s circumstances before recommending treatment, a
bank should assess customers’ financial habits, immediate challenges and long-term ambitions before proposing solutions.
The aim, he says, should not simply be to sell more banking products, but to help customers make informed decisions and build stronger financial futures.
For Eximbank, this approach could deepen relationships with households, entrepreneurs and growing businesses while creating value beyond traditional lending.

As banks serve larger and more diverse customer bases, Harte sees technology and artificial intelligence (AI) as important tools for delivering more personalized services.
Drawing on his experience at international institutions including CBA, Barclays and Santander, he identifies three priorities: understanding customer needs, establishing clear
accountability and equipping employees with the right tools.
He believes Vietnam can adopt modern technologies without necessarily following every stage of development experienced by more mature banking markets. However, technological
advancement alone does not guarantee a better customer experience. “Technology must become invisible,” he said.
For Harte, digital systems should operate seamlessly in the background, enabling faster, more convenient and cost-effective services without sacrificing the personal connection
customers value.
Although Vietnamese banks are investing heavily in digital transformation, he does not believe success depends on being the first to introduce new technologies.
Instead, technology should be chosen according to how effectively it addresses customer needs.
One concept he highlights is “Customer of One,” an approach that recognizes individual circumstances rather than treating large groups of customers as having identical financial
requirements.
AI and data analytics can help banks understand spending patterns, savings goals and financing needs, potentially allowing them to provide more relevant and timely financial advice.
Such capabilities, however, require appropriate safeguards for customer information and responsible data use.
In Vietnam, Harte sees potential in combining physical branch networks with reliable mobile banking services. Digital channels can handle routine transactions, while branches and
employees remain available when customers need personal assistance.
He also sees opportunities in broader digital ecosystems, where consumers increasingly manage everyday transactions and financial activities through connected platforms. These
developments could give banks new ways to provide accessible and relevant services.
Ultimately, Harte believes technology should be judged by whether it helps customers manage their finances more easily and make better decisions. It should support relationships, not
replace them.



Beyond technology, Harte considers corporate governance and organizational culture essential to Eximbank’s transformation.
Reliable customer service, he says, depends not only on frontline employees but also on how effectively teams across the bank coordinate their work. Clear responsibilities, transparent
decision-making and shared objectives can help employees respond more consistently to customers.
This is where corporate governance directly affects the customer experience, in his view. Accountability clarifies who is responsible for decisions and outcomes, while effective
coordination can reduce delays and improve service quality.
Harte believes employees should look beyond their individual departments and understand how their work contributes to broader customer needs. That requires collaboration, continuous
improvement and a willingness to take responsibility for results.
He also sees value in agile working practices, including cross-functional teams, regular communication and clearly defined priorities. These approaches can help employees identify
challenges, coordinate responses and monitor progress.
One question he encourages employees to ask captures this philosophy: “How can I help you achieve what you need this week?”
The principle is not simply about adopting a particular management model, but about creating a workplace in which employees support one another in achieving shared goals.
Employee engagement is also important. When staff have the right tools, clear responsibilities and support from colleagues, they are better positioned to deliver services customers
value.
Harte emphasizes accountability, transparency and sound decision-making as governance priorities, while recognizing that management is responsible for putting these principles into
practice.
He sees governance, collaboration and customer service as closely linked. Effective governance gives employees a foundation for working together, while consistent service helps build
the trust needed for lasting banking relationships.
For Harte, these elements are interconnected.

Harte acknowledges that transforming an established financial institution brings challenges and requires sustained effort.
“The journey has both roses and thorns,” he said.
At Eximbank, he sees opportunities to build on the bank’s history and established customer relationships while strengthening the governance and organizational capabilities needed for
future development.
His ambitions extend beyond technological advancement or the bank’s position in industry rankings. Although he hopes Eximbank will improve its standing in Vietnam’s banking sector, he
considers customer confidence and the value delivered through its services more meaningful measures of success.
He envisions Eximbank becoming one of Vietnam’s most trusted and preferred financial institutions for growing SMEs and households.
Achieving that ambition will require the bank to understand customer needs, make responsible decisions and consistently deliver on its commitments, he said. Progress will depend on
continuous improvements in everyday operations rather than a single breakthrough.
For Eximbank, success would mean more than becoming a stronger bank. It would mean earning a place in the ambitions of Vietnam’s entrepreneurs and helping small businesses become great
ones.