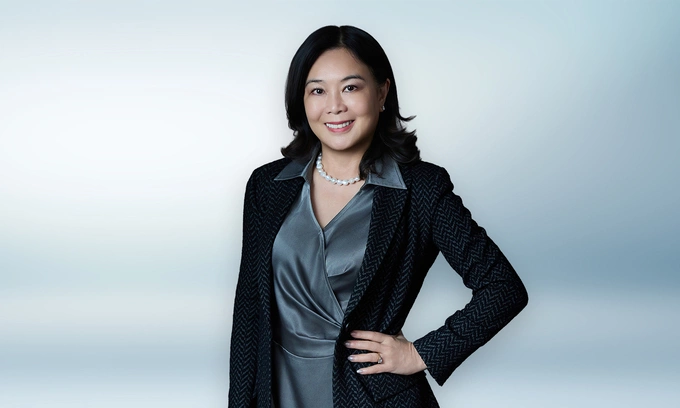
Eximbank independent director Ooi Huey Tyng says the future of banking in Vietnam will depend on understanding customers, using technology to meet their needs and building trust through
sound corporate governance.
More than three decades ago, Ooi Huey Tyng first arrived in Việt Nam as a young analyst for Otis Elevator. Traveling to Hanoi four or five times a year, she was impressed by the people
and the atmosphere.
“I was impressed by the hardworking, friendly people and lovely food around the lake,” she recalled.
When she returned few years ago, as GrabPay’s regional head for Southeast Asia, she found a transformed country, with modern buildings, rising car ownership and a young, digitally
savvy population.
Vietnam’s economic and digital growth reflects that change. GDP expanded 8.02% in 2025, its second-fastest growth since 2011, according to the National Statistics Office under the
Ministry of Finance. Internet penetration reached about 84%, while the country ranked seventh globally in IPv6 adoption.
“The transformation was just wonderful,” she said.
For Ooi, this progress also creates opportunities for banks to rethink how they serve individuals and businesses.
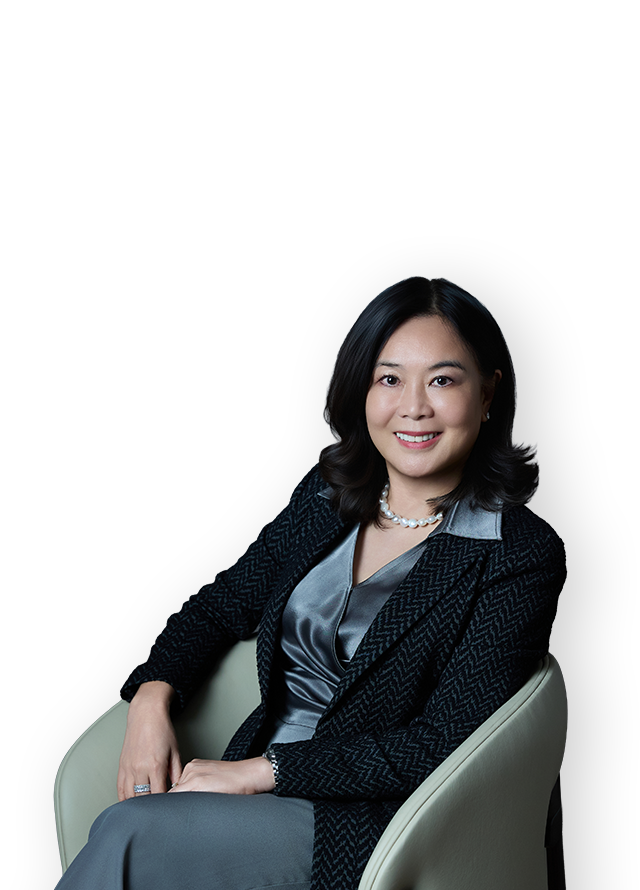
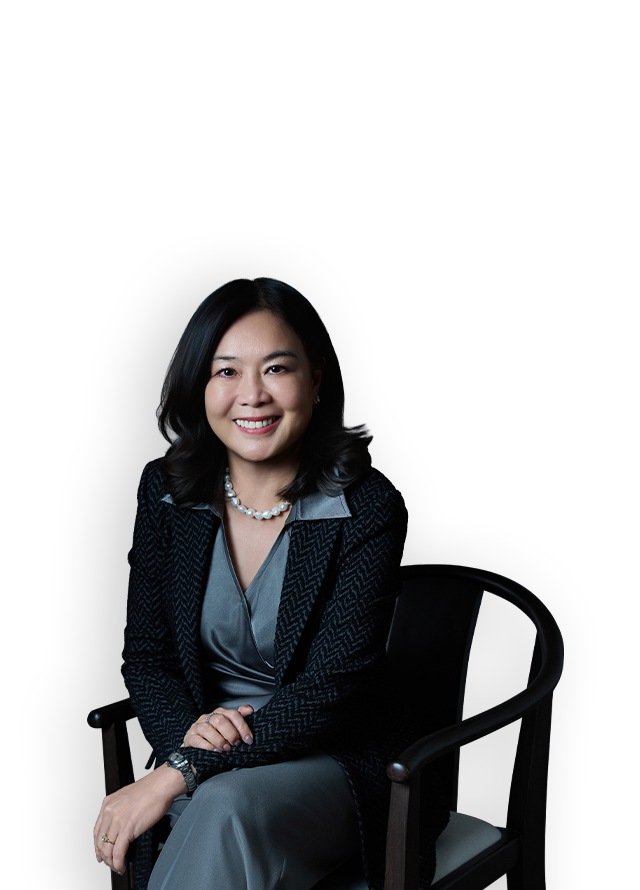
She joined Eximbank’s Board of Directors as an independent member for the 2025–2030 term, bringing more than 30 years of experience in banking, payments and financial technology. Her
career includes positions at Citibank, United Overseas Bank (UOB), DBS, Visa and Grab. She also serves as an independent director at several regional organizations, including on risk,
audit, nomination and remuneration committees.
Ooi said Eximbank’s long history, established customer relationships and efforts to strengthen corporate governance through independent board representation attracted her to the role.
She believes these foundations can help the bank respond to changing expectations as Vietnam’s economy develops.
Understanding tomorrow’s
banking customers
Digital services have reshaped everyday expectations. Consumers can order food, book rides and shop online in a few taps, and increasingly expect similar convenience from their banks.
In Vietnam, non-cash transactions rose 42.21% in volume in 2025, while internet-based transactions increased nearly 54%, according to the State Bank of Vietnam.
“Digital expectations are compared against shopping, ride-hailing and food apps where instant gratification is mandatory,” Ooi said.
Customers now compare banks not only with other financial institutions but also with the speed, convenience and personalization of the digital platforms they use daily. But Ooi said
convenience alone is not enough.
As Vietnam’s economy grows, financial needs are becoming more diverse, particularly among young affluent consumers, entrepreneurs and small and medium-sized enterprises (SMEs).
The 2026 economic census by the National Statistics Office recorded 859,048 operating enterprises generating revenue at the end of 2025, employing nearly 17.6 million people. Vietnam
also had well over five million household businesses.
These groups have different financial circumstances and priorities, requiring banks to move beyond standardized products. For Eximbank, Ooi said understanding the “customer of
tomorrow” means tailoring services to different segments and adapting as their needs change.
She sees data infrastructure as essential to this approach, helping banks understand customer behavior and develop more relevant financial solutions.
SME working capital financing is one potential application. Many small businesses struggle to secure loans because they lack traditional collateral. However, merchants operating
through digital platforms generate transaction and revenue data that can help lenders assess their financial health.
Drawing on the GrabFood merchant model, Ooi described how lenders could use daily cash flow and sales records to assess creditworthiness, provide working capital and collect repayments
through small daily or monthly deductions.
Such an approach could make financing more accessible and flexible for eligible businesses. However, it is an illustrative model, not an existing Eximbank product or announced plan.
Any such lending would still require credit assessment, risk controls and regulatory compliance.
For Ooi, the principle is to start with customers’ financial challenges rather than the products banks want to sell.
Technology as a tool,
not an end goal
As banks invest in artificial intelligence and digital transformation, Ooi believes technology should be judged by how well it improves customer experiences.
Investing in new systems does not necessarily make banking easier. Meaningful transformation requires banks to identify customers’ difficulties and improve processes before choosing
the technology to address them. The most valuable solutions are not necessarily the newest or most sophisticated, but those that help customers complete transactions, access relevant
services and make informed financial decisions.
Ooi also encourages banks to learn from technologies already tested across the industry rather than pursue every emerging innovation. Institutions can assess proven solutions and
determine which fit their customers, capabilities and long-term strategies.
For Eximbank, this could offer a practical way to modernize while managing costs and uncertainty.
Ooi identifies three foundations for successful transformation: a shared vision and strategy, system modernization driven by customer needs, and an organizational culture that puts
customers first.
These priorities require alignment across the bank, from the Board of Directors and management to employees serving customers, while preserving the distinction between governance
oversight and daily operations.
Her experience in banking and fintech has also shaped her approach to balancing innovation and risk. Drawing on lessons from DBS, she emphasizes what she calls intelligent risk-taking:
recognizing uncertainty while ensuring risks are understood and managed.
This does not mean adopting new technologies without safeguards. Instead, banks should test ideas on a limited scale, with clear objectives, risk parameters and oversight, before
considering wider implementation. Solutions should be assessed for customer benefits and commercial potential, as well as security, regulatory compliance, financial risks and
operational resilience.
Ooi believes innovation and risk management should reinforce each other, allowing banks to explore new approaches while protecting customers and the institution.
Protecting trust through
stronger governance
Despite her experience in digital payments and fintech, Ooi believes established banks have an advantage that technology alone cannot easily replicate: customer trust.
Her work in fintech has shown her the challenges newer platforms face in building the confidence that banks develop through longstanding customer relationships. For Eximbank, she
considers that trust one of its most valuable assets.
Customers entrust banks with savings accumulated over years, money supporting their families and capital used to run businesses. Protecting those funds requires reliable services,
sound governance, transparency and accountability.
Ooi said corporate governance goes beyond formal policies and structures. It establishes clear responsibilities, supports informed decisions and ensures risks are identified and
managed.
The Board of Directors provides strategic direction and oversight, while management is responsible for daily operations and implementing the bank’s strategy. As an independent
director, Ooi sees her role as ensuring major decisions receive appropriate scrutiny, risks are properly evaluated and the institution’s long-term interests remain central.
Transparency and accountability also help build confidence that decisions follow appropriate processes and responsibilities are clearly defined.
Ooi views governance as an ongoing process of institutional development, rather than simply correcting shortcomings. She hopes to contribute international perspectives to help Eximbank
strengthen its governance standards and maturity, with the ambition of progressing beyond prevailing industry benchmarks.
This is increasingly important as banks adopt new technologies, develop personalized services and explore innovative approaches to financing. While these developments can create value,
they also require careful attention to data protection, financial risks and depositors’ interests.
Customers may never see decisions made in the boardroom, but they experience their impact through the reliability of banking services and the confidence they place in financial
institutions.
Ooi envisions an Eximbank where customers can handle everyday transactions easily through digital channels while still receiving personal financial advice at branches when needed.