The number of food service outlets rose to about 329,200 by the end of the second quarter from around 299,900 a year earlier, adding nearly 30,000 outlets to the market, according to a recent report by iPOS.vn and Nestlé Professional.
That means a larger share of total industry revenue is being spread across a significantly greater number of businesses, leaving many individual operators with little improvement in sales despite growth in the overall market.
The divergence underscores the pressure facing Vietnam’s F&B sector after a year of intense consolidation, as new outlets increasingly compete for the same pool of consumers.
Nguyen Do Anh Quan, brand director at iPOS.vn, said the first half of the year is typically a period of market consolidation.
“After the Lunar New Year holiday, outlets with weak cash flows or an unstable operating foundation often have to leave the market,” Quan said.
The total number of outlets declined just 0.1% from the end of 2025, suggesting closures have slowed while new openings have been sufficient to offset most businesses leaving the market, he said.
“This can also be seen as a sign that the market is gradually becoming more stable, while F&B businesses are beginning to operate in a more structured, professional and planned manner,” Quan said.
|
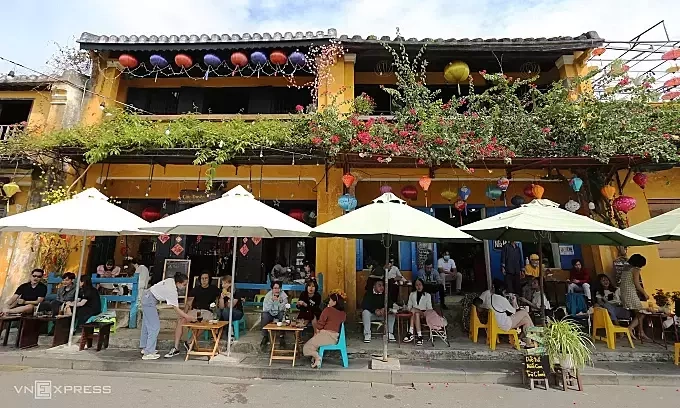
A cafe filled with customers in the former Quang Nam Province. Photo by Read/Dac Thanh |
The revenue growth also needs to be viewed against seasonal and price factors. The 2025 Lunar New Year’s timing split the peak shopping season between December 2024 and January 2025 while most of the peak consumption period for 2026’s Lunar New Year fell within the first half.
Consumer prices rose 4.4% year-on-year on average in the first half of 2026. This suggests that part of the increase in F&B revenue reflected higher prices and broader macroeconomic factors, rather than a corresponding increase in real consumer demand.
The strain on individual businesses is reflected in a survey of 481 F&B operators across 15 provinces and cities.
About 43% reported lower revenue than a year earlier. Of these, 27.5% recorded declines of 5-20% but remained in operation, while 15.2% suffered declines of more than 20% and faced significant difficulties.
At the other end of the spectrum, 20.2% of businesses reported revenue growth of more than 5%, while 37.1% saw relatively stable revenue.
The figures suggest that consumer spending has not disappeared from the market, but is being allocated more selectively. Even businesses operating in the same area and facing similar cost structures and customer demographics can post sharply different results.
Vu Thanh Hung, CEO of iPOS.vn, was quoted by I give you (Investment) newspaper as saying that consumers were still eating and drinking outside the home and were even spending more, but were becoming more selective and demanding.
“Total spending has not left the market, it has simply changed destinations,” Hung said.
He said the reallocation of consumer spending helps explain why businesses operating under similar conditions have achieved markedly different results over the past six months.
The divergence is particularly visible between F&B businesses. While the share of outlets reporting declining revenue was broadly similar in the two segments, food businesses recorded stronger growth. Some 25.6% of food businesses reported growth of more than 5%, compared with 15.8% among beverage outlets.
Food businesses can rely on demand for meals, group dining and bundled products to increase average bill values. Beverage outlets, by contrast, face intense competition for each upsizing decision, additional topping or attempt to persuade customers to choose a higher-priced drink.
Pressure is also coming from a growing number of mass-market and low-cost models. Some 88.5% of surveyed owners said they had clearly seen such models emerge around their business areas, while about 58.2% said they had actually felt the pressure.
Some 35.4% of outlets kept their existing sales approach and accepted losing some customers, while 22.8% proactively cut prices, introduced promotions or added lower-priced products.
The trend suggests low-cost models have not yet forced the entire market into across-the-board price cuts, but are gradually taking customers away from outlets that are slow to adapt.