AceVector’s Dull D-Street Debut
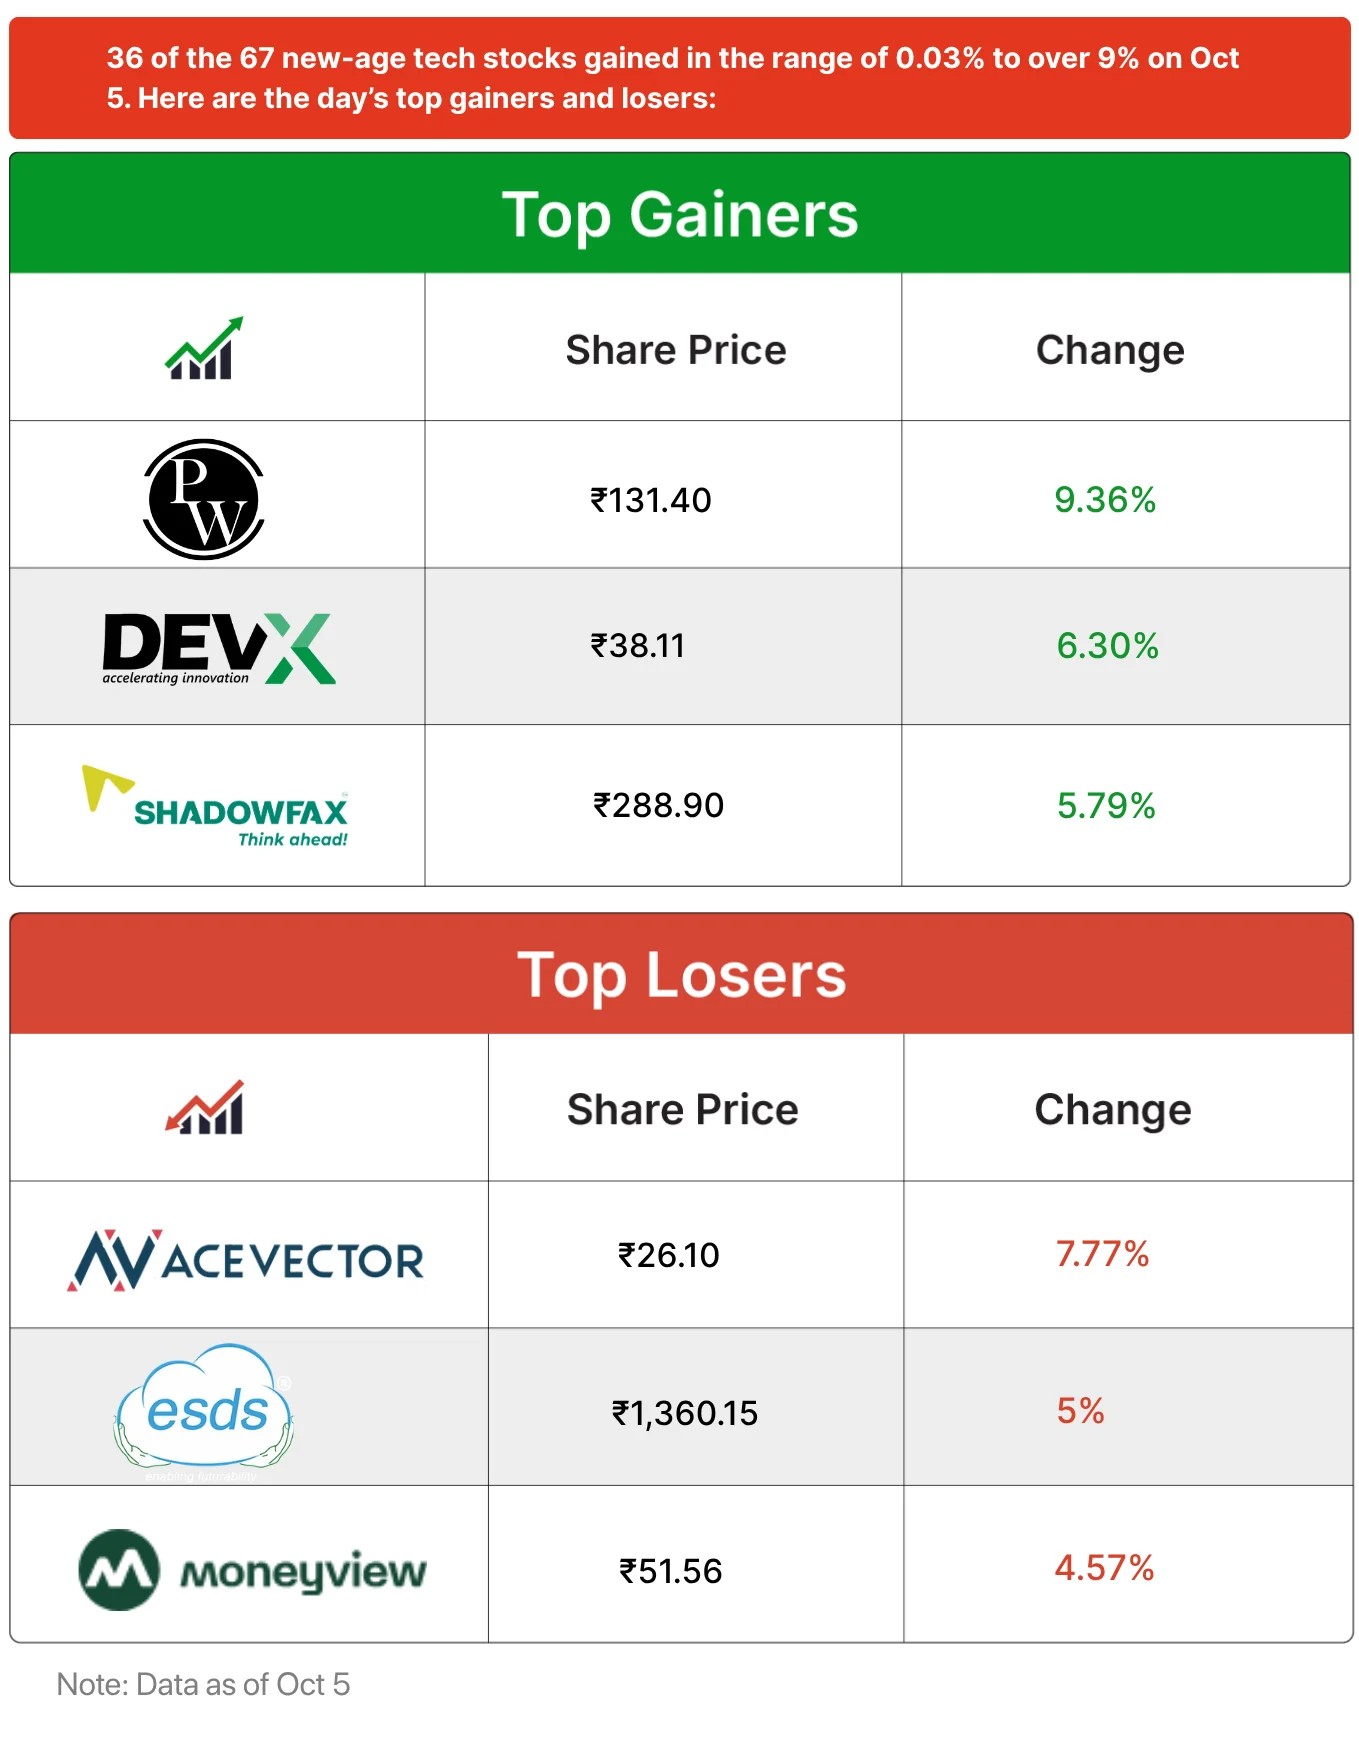
AceVector stepped onto Dalal Street with a weak show. Shares of the Snapdeal parent listed at a discount yesterday, before slumping even lower to finally close its first trading on a sombre note. But the subdued listing did not come as a surprise.
A Rough Debut: AceVector’s shares listed at ₹28.30 on the BSE, a discount of 11.6% to its issue price of ₹32 per share. On the NSE, the stock debuted at ₹28.32, an 11.5% discount to the IPO price. The downward trend continued as the shares finally closed the day more than 18% lower than the issue price. So, what went wrong with its IPO?
The Looming Shadow: AceVector’s IPO fumbled on persistent losses, negative operating cash flows and intense competition. Brokerages had previously also flagged thin take-rates as well as high marketing and logistics costs as key risks. With a modest 4.93X subscription, 6% GMP and limited institutional interest, investors remained wary of AceVector’s path to profitability despite Unicommerce’s SaaS growth and Snapdeal’s value-commerce niche.
The Meesho Gap: Despite strong brand recall and a focus on value shoppers, Snapdeal’s scale lags far behind Meesho’s. In FY26, Meesho reported NMV of ₹41,560 Cr, about 38X compared to Snapdeal’s ₹1,093.1 Cr. The Vidit Aatrey-led startup also handled 264.29 Mn annual transacting users in FY26 compared to Snapdeal’s 12.16 Mn users. Experts had also flagged that Snapdeal’s affordability and AI niches were no longer a differentiator in a crowded market.
The Unicommerce Advantage: While Snapdeal struggled with scale, AceVector’s listed SaaS arm continues to be a key growth engine. In FY26, its revenue jumped 51.6% YoY to ₹204.3 Cr, far outpacing Snapdeal’s 17.5% growth. Analysts had seen this higher-margin business as a potential valuation anchor, although it remains too small to offset Snapdeal’s challenges.
While it would be interesting to see if the company picks up pace in its post-IPO era, here is all about AceVector’s weak listing on the D-Street…
From The Editor’s Desk
💼 Founders Pledge Stakes
- Ola Electric founder and CMD Bhavish Aggarwal has pledged a 4.32% stake in the EV maker to fund his participation in the company’s upcoming ₹1,000 Cr rights issue. The arrangement involves pledging 20 Cr shares in favour of CTL Trusteeship Ltd.
- Separately, ideaForge’s promoter and CEO Ankit Mehta has pledged 2.8 Lakh sharesor 0.56% of the company’s total share capital, for “personal financial requirements.” The pledged shares were worth around ₹20 Cr.
- The developments come as Ola Electric’s board recently cleared a broader ₹1,500 Cr fundraising plan. There appears no clarity on whether or how it will raise the remaining ₹500 Cr. Meanwhile, ideaForge recently raised ₹500 Cr through a QIP in July.
💰 Leverage Edu Eyes ₹500 Cr
- The study abroad platform is exploring a ₹500 Cr pre-IPO fundraise. The startup has already held talks with a couple of global PE firms and expects to close the round soon.
- Leverage Edu now plans to file its DRHP by the end of next year. The edtech startup is currently out in the market to finalise investment bankers for the IPO. This comes as the company is targeting ₹600 Cr in revenue in FY27.
- Inc42 had earlier reported that Leverage Edu is planning a ₹2,000 Cr to ₹3,000 Cr IPO, comprising a fresh issue of shares and an OFS. The startup is targeting a valuation of over $900 Mn for the IPO. It also turned EBITDA profitable in FY26.
🚀 Top Investors In Q3 2026
- The Indian startup funding market remained selective in Q3 2026. Total funding saw a meagre uptick, VCs backed fewer startups, the pool of active investors shrank and venture debt continued to be the most prominent source of capital.
- Venture debt firm Stride Ventures emerged as the most active investor in Q3 with 38 deals, followed by Alteria Capital with 31. The duo have maintained this lead throughout 2026.
- Among equity investors, 3one4 Capital topped the list with 19 investments in Q3, followed by the likes of Rainmatter with 16, IvyCap Ventures with 15 and Antler with 14.
🎓 PhysicsWallah’s Lending Retreat
- The listed edtech major’s subsidiary FinZ Finance has agreed to sell its ₹95.79 Cr loan portfolio to Auxilo Finserve. The deal, which is expected to result in partial closure of PW’s lending operations, will conclude in the next two months.
- PhysicsWallah said the sale is part of its broader push to optimise capital allocation and focus on its core business. Lending would now be facilitated via third-party NBFCs to reduce balance sheet exposure and credit risks.
- In May, PW approved a ₹120 Cr infusion into FinZ Finance. However, the decision put pressure on the company’s shares and raised concerns about its capital allocation priorities. The listed edtech then said that it would retreat from the lending space.
🪴 Marico Ups Stake In Plix
- The FMCG giant has acquired an additional 24.09% stake in the plant-based nutrition brand for ₹1,012.03 Cr in an all-cash deal. With this, Marico’s total holding in the startup has now increased to 84.09%.
- Marico will now acquire the remaining 14.09% stake in Plix by July 2027. The consideration for this tranche will include a base amount of up to ₹592 Cr, along with additional payments linked to milestones.
- Separately, Walmart-owned Flipkart has picked up a minority stake in B2B travel tech startup TravClan for an undisclosed amount to bolster its international travel offerings, expand holiday packages and enhance on-ground support across.
Inc42 Markets
Inc42 Startup Spotlight
Can Physioplus’ AI Stack Track India’s Recovery Journey?
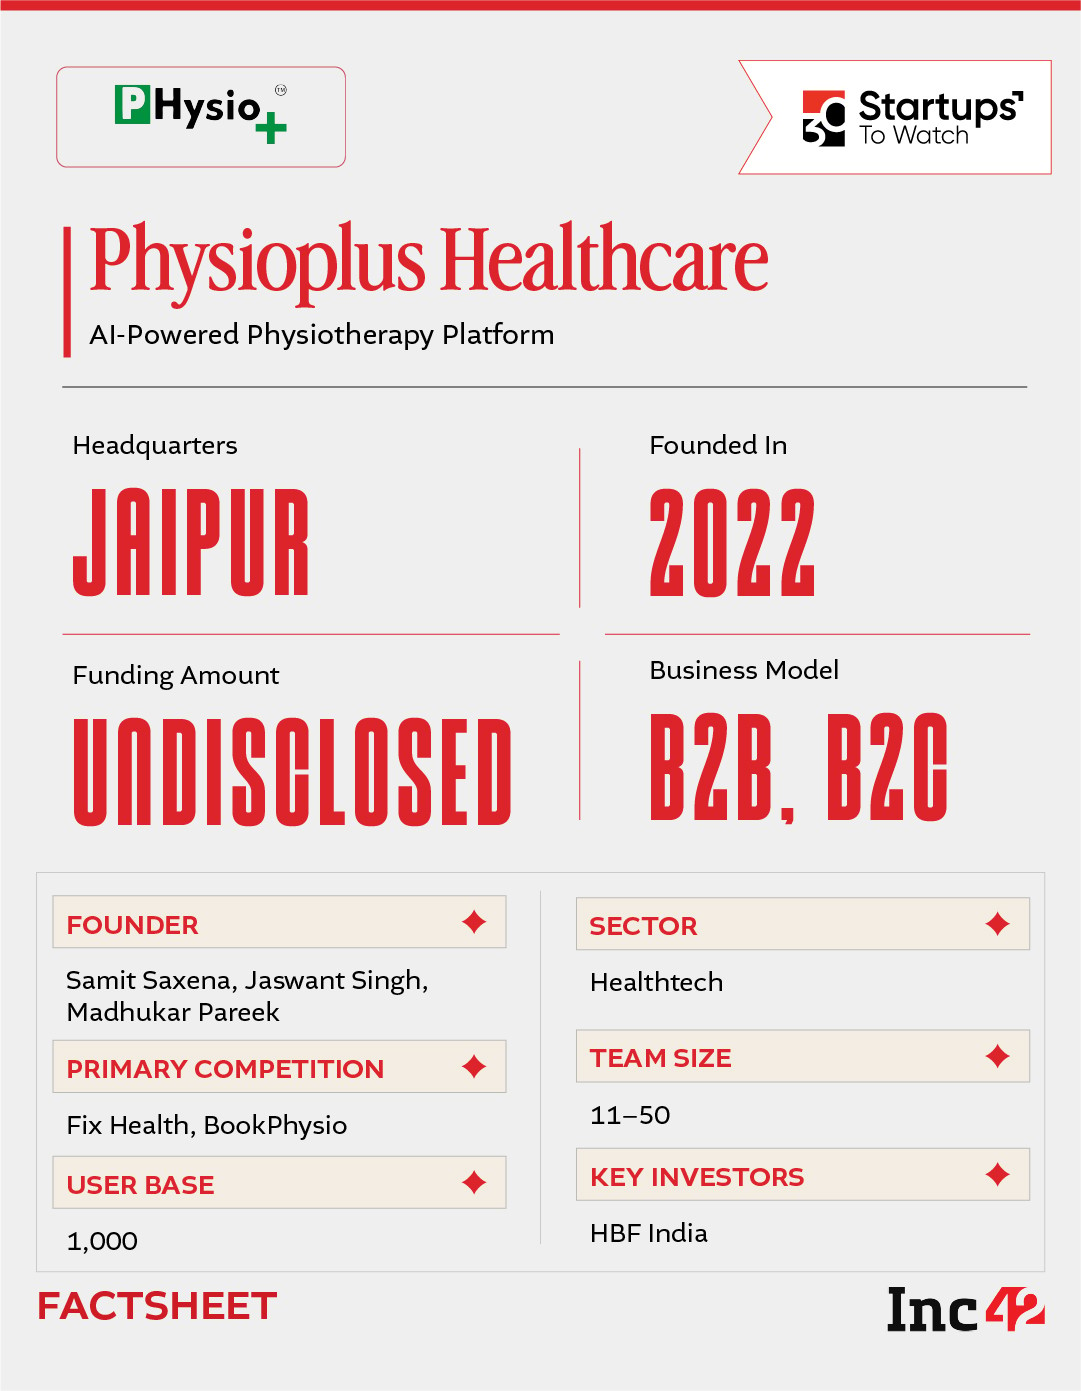
Physiotherapy often breaks down between appointments. While patients struggle to follow exercises, therapists lack real-time visibility into progress. To solve this, Physioplus is building a digital layer that keeps assessment and recovery tracking connected beyond the clinic.
A Digital Coach: Founded in 2022, Physioplus’ AI-powered platform helps patients discover physiotherapists, book consultations, request home visits and receive support for chronic pain and post-surgery rehabilitation. The platform is designed to make access more convenient while helping clinicians understand a patient’s history before treatment begins.
The Rehabilitation Stack: For practitioners, Physioplus combines digital practice management, patient records, clinical assessments, documentation and tech-enabled monitoring. Its monitoring layer also supports home-based rehabilitation by capturing exercise adherence, pain changes and functional progress over time.
Growing Steadily: Physioplus claims to have so far onboarded over 1,000 patients. It is now focusing on scaling product development, expanding its physiotherapist network and fueling growth across India. With the homegrown digital health and rehabilitation market projected to become a $14.8 Bn opportunity by 2033, can Physioplus make physiotherapy more measurable and consistent beyond the clinic?
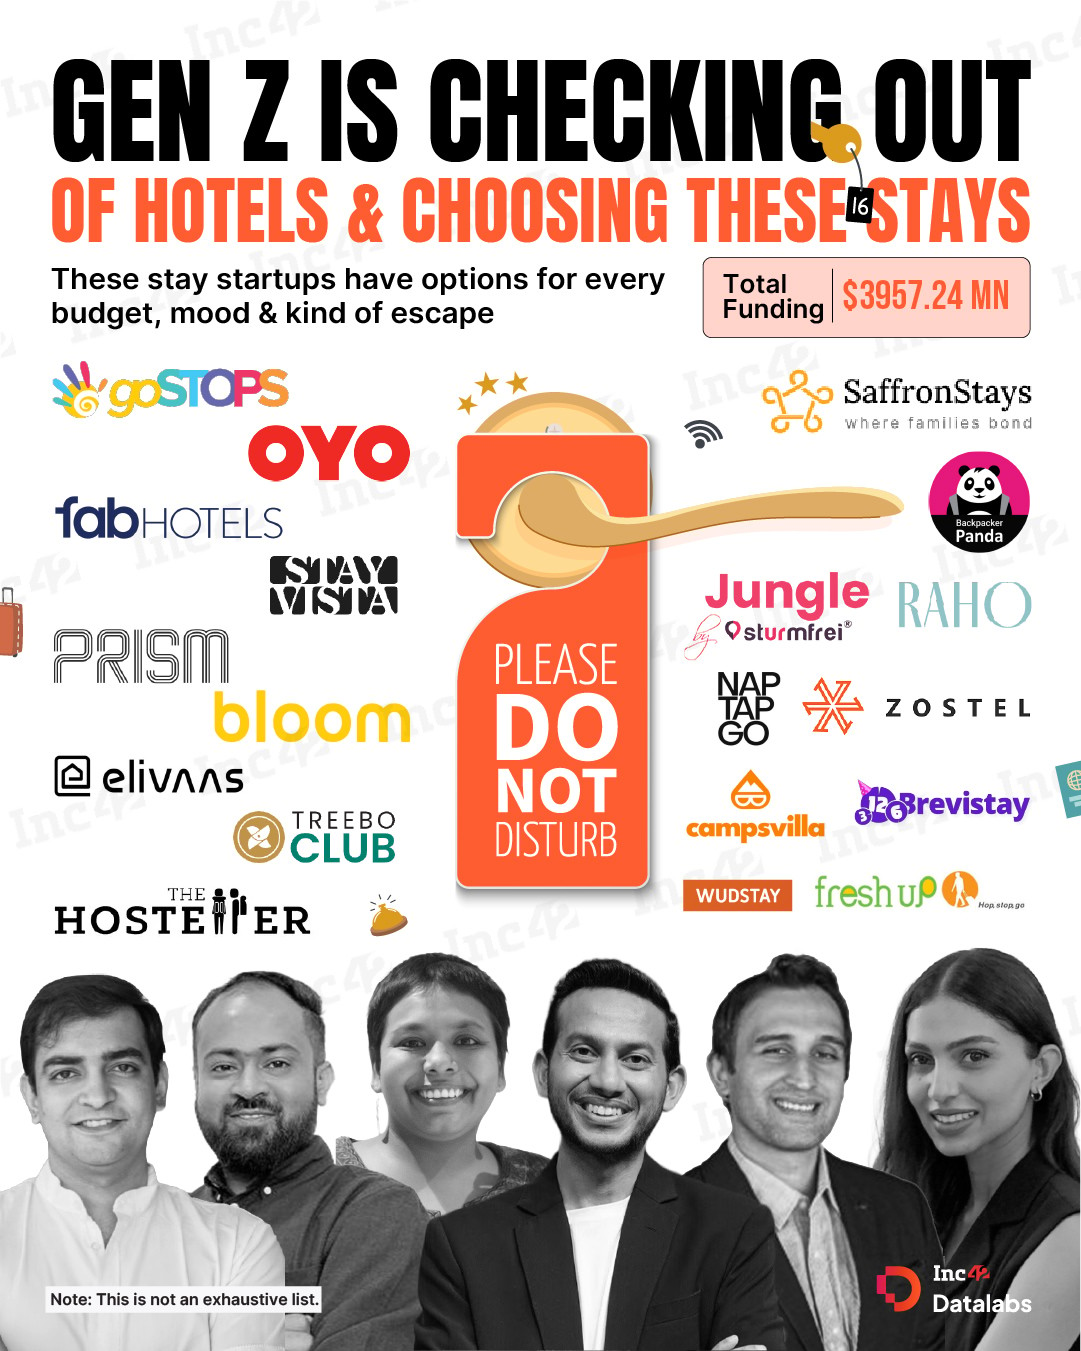
Infographic Of The Day
Gen Z isn’t booking rooms anymore, they’re booking experiences. From hostels with a rooftop to boutique homestays that don’t feel like an ad, here is how India is changing the way it travels and stays…